A note before you read this: This reflects my personal experience and the stock’s fundamentals as of May 2021 (originally bought in November 2019) — genuinely old given how quickly markets move. The ₹1000 price target mentioned below is my own 2021 opinion, not a current forecast. This isn’t current investment advice. Check today’s price and financials before making any decision, and consider speaking with a SEBI-registered financial advisor for personalized guidance.
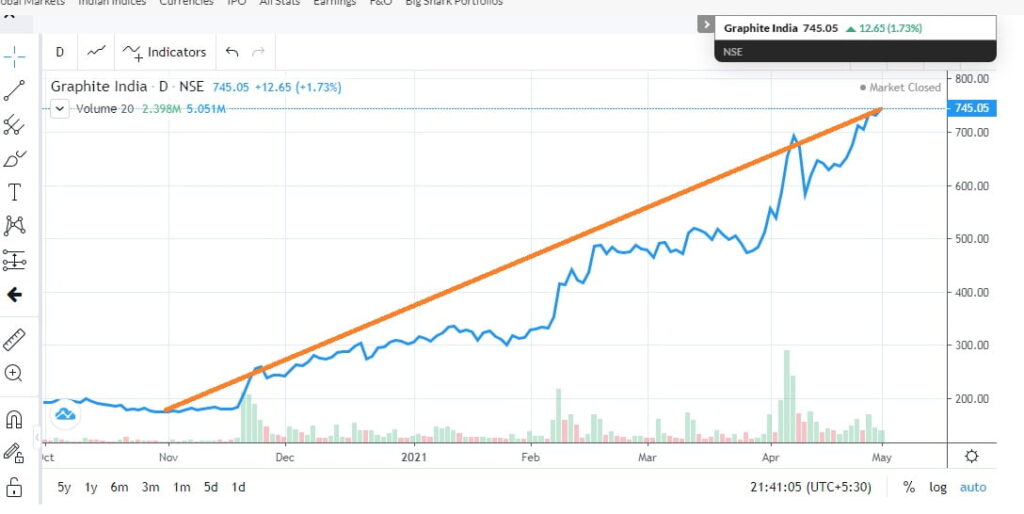
I bought Graphite India Ltd share in November 2019, before the covid market crash. I bought this share blindly because it was a dividend-paying stock. It was during my initial days in the share market, and I was looking for strong market capital shares and shares that paid dividends.

As of May 2021 (19 months after my purchase), the share had reached nearly 200% higher than my buy price. This was my own specific outcome at that point in time, not a typical or guaranteed result — individual stock returns vary enormously and past performance on one position says nothing about future results.
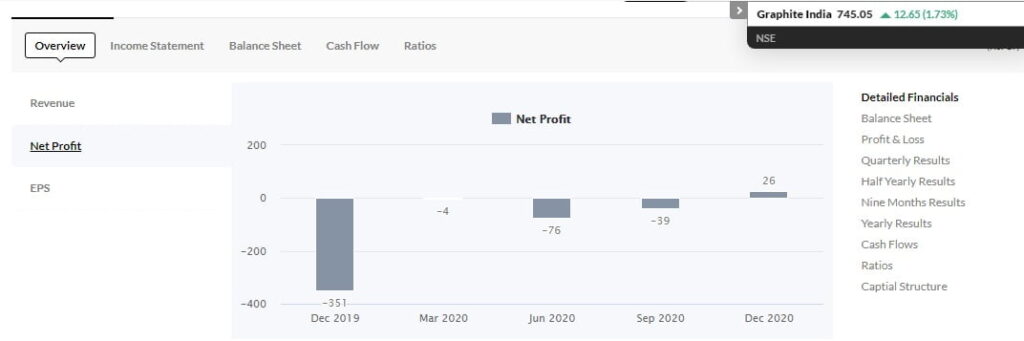
At the time, the business had grown its net profit and I believed it had the potential to grow back to its older share price.
Founded in 1962, Graphite India Ltd was a pioneer in manufacturing graphite and carbon electrodes in India, later diversifying into other carbon-based products for domestic and international markets. It started as a joint collaboration with a US company before merging into one entity.
Graphite India’s products are mainly used by heavy industries — steel, auto, and infrastructure — so its performance is closely tied to those sectors, particularly steel. As an amateur trader, I generally chose shares with a large market cap and a dividend-paying history. This particular share had traded above Rs 1000 in 2018 before falling due to business losses, which I saw as an opportunity given what I judged to be otherwise solid fundamentals at the time.
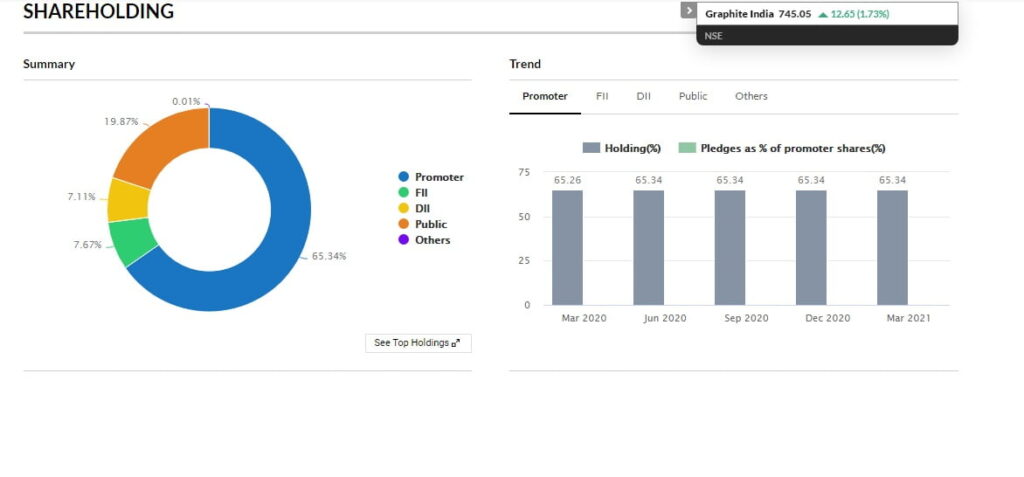
At the time, the promoters held more than 60% of the company.
At the time of writing (2021), I believed the share price fluctuation was mainly due to the broader slowdown in auto and infrastructure sectors, and I personally believed the stock might return to around Rs 1000 once those industries recovered. This was my own opinion at the time, not a verified forecast — I never followed up publicly on whether that played out, so please check the stock’s actual historical performance yourself rather than relying on this prediction.